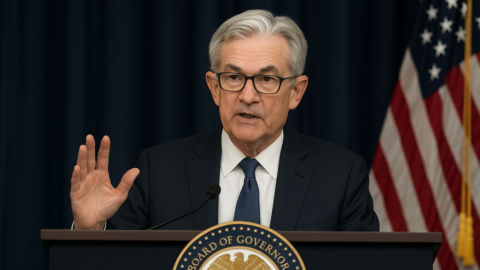
Wait and see. There is nothing else to do in the markets today: sit on the sidelines and wait for one of the most news-heavy days of the year which could give the market trends. Today It's Fed Day, with the last appearance of President Jerome Powell, but it is also the day of the quarterly of 5 of the Magnificent Seven ofartificial intelligence USA. Meanwhile the price of the Petroleum it retreats slightly this morning but remains over $ 111, with investors weighing the news of the The United Arab Emirates' surprising exit from OPEC after 60 years. The diplomatic impasse between Washington and Tehran the end of the war continues to weigh on the markets. Wall Street Journal reported yesterday that Trump has instructed his aides to prepare for a prolonged blockade of Iran. asian bags have changed little, after that Wall Street collapsed yesterday because fear of the boom in artificial intelligence has crept in again. European stock exchanges are seen opening slightly higher.
Oil: June contract expiring above $111, July contract at $104
The prices of Petroleum fell slightly this morning after a multi-day rally, as investors weigh the consequences of the surprising decision of the United Arab Emirates to leave OPEC after 60 years, while the blockade of the Strait of Hormuz continues to support the market.
Oil futures Brent with expires in June fell 1 cent to $111,25 a barrel this morning, after being higher for the previous seven sessions. The June contract expires tomorrow, while the July, the most traded, is down 28 cents at $104,12. Some analysts see the surprising decision by the United Arab Emirates as a possibility of more solid offering when the country will be free from the group's production quotas, even if the effect will not be immediate, as additional barrel supplies may not be deliverable in the short term due to the ongoing blockade in Hormuz.
It's the day of the Fed, Powell and Warsh
It's the Fed's day, and it seems increasingly certain that it will be the Fed's last term. Jerome Powell as chairman. By the end of the Federal Open Market Committee's work today, the Senate will vote on the confirmation of Kevin Warsh, Trump's choice, paving the way for one of the most crucial periods in the history of the world's most powerful central bank. Federal funds rate futures point to a 100% probability of maintaining rates, with no monetary policy changes expected until well into 2027. However, with the FOMC appears more divided than ever, questions remain about like Warsh He will manage the relationship between the central bank and the White House, as US President Donald Trump continues to call for rapid and aggressive rate cuts. It is also unclear whether Powell will remain on the Fed's Board of Governors after his term as chairman officially expires on May 15. Powell's press release and subsequent press conference will be closely scrutinized to understand policymakers' views on the matter. inflation risk linked to the surge in energy prices due to the war.
Wall Street fell sharply yesterday as fears of an AI boom due to OpenAI return. Expectations are high for Microsoft, Alphabet, Amazon, and Meta.
Wall Street closed down yesterday, moving away from its all-time closing highs, as the fears about the boom in artificial intelligence, weighing on the technology stocks while we wait for five of the most important companies in the sector to publish their quarterly results. The actions of semiconductor industry, which have surged by more than 40% since the beginning of the year, have weighed particularly heavily on Nasdaq, which suffered its biggest daily percentage loss in a month, closing down 0,90%. S & P 500 closed down 0,49%, Dow of 0,05%
According to an article in the Wall Street Journal, OpenAI is seeing a decline in weekly users and revenue, raising concerns about the AI giant and parent company's ability to ChatGPT to support its huge data center expenses. Oracle infrastructures whose reliance on OpenAI for its cloud computing ambitions is under scrutiny, fell by 4,1%. Even Chip Titles have dropped, including Nvidia, AMD, and Broadcom which closed down between 1,6% and 4,4%. CoreWeave, tied to Nvidia, fell 5,8%.
First quarter data season kicks off today: Microsoft, Alphabet, Amazon and Meta will release their reports today, with investors analyzing their massive capital spending plans to build data centers and other infrastructure to support AI applications. Tomorrow, however, it will be the turn of Apple with the recent change of its CEO, following the departure of Tim Cook. According to analysts, these companies represent approximately 44% of the total market capitalization of the S&P 500 index. But there will also be data on AbbVie e Qualcomm.
General Motors rose 1,3% after the automaker beat quarterly earnings estimates and raised its full-year profit forecast, boosted by a strong U.S. auto market and an expected tariff rebate. Ups fell 4,0% even as the parcel delivery company reiterated its full-year revenue target, balancing soaring fuel costs with improving business.
Coca-Cola rose 3,9% following the release of better-than-expected quarterly results. The beverage giant downplayed the impact of high oil prices and raised its full-year profit target.
Asian markets are mixed. Japan is closed for holidays. Defense sector stands out on the Kospi.
Asian stocks are mixed and show minimal changes, also awaiting the day's key data. After some fluctuations, the MSCI Asia Pacific Index settled around parity (+0,1%).
In JapanMarkets are closed for a national holiday: Shōwa no Hi, or Shōwa Day, is celebrated. This holiday marks the beginning of Golden Week, a period of consecutive holidays that fall between May 3rd and 5th, and celebrates the birthday of Emperor Hirohito (Shōwa period), a time dedicated to reflection on this turbulent yet transformative period in his history.
In China The CSI 300 is up 0,6%; Hong Kong's Hang Seng is up 1,4%. Victory Giant Technology Huizhou, a Chinese supplier company Nvidia, closed the first quarter with sales up 28% year-over-year, thanks to increased demand for printed circuit boards used in AI servers. Foxconn Industrial Internet lost up to 6% after publishing lower-than-expected quarterly results. Nio instead it rose to 8% Hong Kong, after the start of pre-orders for the new SUV.
In Seoul, the Kospi gains 0,7%. In the index, dominated mostly by technology stocks, the ones that stood out today were the defense titles, driven by Hyundai Rotem, which rose 8% after the announcement of a contract in Poland for the local production of tanks. Taiex of Taiwan: -0,5%. Straits Times of Singapore: -twenty%.
European stock markets opened slightly higher. At the Milan Stock Exchange, eyes were on Nexi, Eni, and MPS.
European stock markets are expected to open slightly higher: the Eurostoxx50 futures are up 0,19%.
Pernod Ricard and Brown-FormanMerger talks ended after the French liquor company and the Kentucky-based company that owns Jack Daniel's whiskey failed to reach a mutually satisfactory agreement.
Deutsche Bank closed the first quarter of 2026 with record profit: the net profit after taxes rose 8% to €2,2 billion. Net profit attributable to shareholders, €1,9 billion, exceeded analysts' estimates of €1,77 billion and the €1,8 billion recorded in the same quarter of the previous year.
AdidasOperating profit in the first three months of 2026 rose 16% to 705 million euros, exceeding the 647 million euros expected by analysts in a company survey, compared to 610 million euros a year earlier.
ubsThe largest Swiss bank reported net profit attributable to shareholders of $3,0 billion in the first quarter of 2026, up 80% year-over-year and exceeding the average estimate of $2,3 billion in a survey of analysts conducted by the company. The profit surge was driven by strong trading activity.
Eni. He informed Business Minister Adolfo Urso that he had selected an advisor to identify an industrial entity interested in acquiring the Brindisi cracking plant (for processing hydrocarbons). According to a source, the selected advisor is JP Morgan. HSBC raised its target price to 22 euros from 21, with a hold confirmed.
PsCEO Luigi Lovaglio intends to call a meeting for the merger with Mediobanca between June and July with the aim of closing the deal in the fourth quarter, he writes. Mf which cites Riccardo Mulone, head of UBS Italy, as a possible future CEO of the "new" Piazzetta Cuccia in place of Alessandro Melzi d'Eril.
nexiPrivate equity firm CVC Capital is reportedly considering a €9 billion bid for the Italian payments group. This is according to the Financial Times, citing sources familiar with the matter. The shareholders' meeting to discuss the financial statements is being held today.
SaipemBernstein raised its target price to 4,96 euros from 4,61. Outperform confirmed.
SnamBerenberg raised its target price to 6,6 euros from 5,3. Hold confirmed.
Stellantis. It publishes its quarterly results tomorrow.
EdisonFrance's EDF has postponed any decision on the sale of a stake in its Italian subsidiary after the war in Iran disrupted supplies of liquefied natural gas from Qatar that Edison imports. This was announced by Reuters four sources familiar with the matter.
FerragamoJefferies initiated coverage on the stock with an underperform rating and a target price of €5,5.