Skyrocketing Christmas expenses, oil and copper prices as well. Apple in trouble, banks and General Motors discover that the US tax reform it can be a boomerang. There is no shortage of news at the end of the long Christmas break, enough to animate the short week of price lists, the last of a year full of satisfactions which will close, between today and tomorrow, with the first Italian Treasury auctions of 2018.
CRUDE OIL ABOVE 66 DOLLARS, COPPER AT HIGH
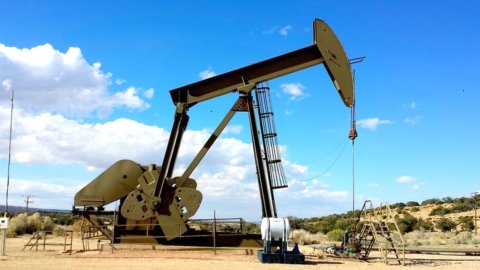
The rally in commodities characterized the Asian markets this morning. The explosion of the pipeline leading to the Sidra terminal on the Libyan Mediterranean coast caused a sharp drop in production (from 260 barrels to no more than 70) with immediate repercussions on oil prices. The WTI shot past 60 dollars last night, while Brent traded this morning at 66,63 dollars (+2,3%). The price increase was transferred to oil quotations. On Wall Street there were increases between 0,8 and 2.5% for Chevron, Exxon and Conoco Philips.
The price of copper is also on the rise, jumping to a 3-and-a-half-year high at 7,210 dollars a ton, pending a recovery in Chinese demand.
Chinese stock markets are advancing: Shanghai and Shenzhen, with an increase of 0,3%, are about to close 2017 with a gain of 22,5%. Hong Kong closed, which in its last session, on the 22nd, revised upwards the gain for the year: +34,4%, a record since 2009.
Positive annual performance also for the Japanese Nikkei (+22,5%), supported by excellent data on employment (the unemployed fell to 2,7%, the lowest since 1993) and inflation, timidly recovering to 0,9 .0,2%. This morning the Tokyo Stock Exchange is down slightly (-XNUMX%) in line with the closure of Wall Street.
SUPER CHRISTMAS IN USA, BUT WALL STREET IS WEAK
In fact, conflicting signals conditioned the American markets. The Dow Jones finished the session imperceptibly down 0,03%, S&P 500 -0,11%. Worse was the Nasdaq (-0,3%).
The positive notes came from the Christmas expenditure front. Christmas sales have never been so good for both e-commerce and traditional commerce. Purchases via the web, according to projections on the data processed by the MasterCard observatory, grew by 18,1%, favoring the rise of Amazon (+0,7%), the only Internet giant in positive territory. Department stores are also growing strongly, with increases in turnover between 12 and 17%. Kohl's (+4,5%) and Macy's (+5%) rose on Wall Street. Record earnings also for Footlocker and Nordstrom.
IPHONE X SALES DISAPPOINT
The negative news comes from the technological price lists, starting with Apple (-2,5%) after the publication of a report by the Taiwan Economic Daily which shows that iPhone X shipments are far lower than expected: no more than 30 million pieces against the 50 million expected. The descent involved Apple's suppliers, from Broadcom to Skyworks Solution, but ended up infecting the entire technology sector, including Facebook, Google, Alphabet and Netflix. After all, the big names in Silicon Valley are among those who will benefit the least from the tax reform, because they already pay an average of only 24% of profits today.
Speaking of taxes, the Financial Times has found that Trump's reform will have a heavy side effect for banks that still benefit from tax credits after the 2008 crisis. The deductions, in fact, will have to be applied to the new rates of 21 % and not on 35%, as in the past. The phenomenon will also affect General Motors (14 billion credits).
BITCOIN ON THE RISE, BUT ISRAEL'S STOP WEIGHTS
The emotions continue to burst on electronic currency Bitcoin, rebounded this morning to 15.865 dollars, still far from the highs (19.666) of December 17th.
Israel's stock market regulator has launched proceedings to ban companies whose "core services" are in digital currencies from being listed on the local exchange, while those already listed but which will shift the majority of their operations to digital money services will be removed from the list. The reasons are due to fears of speculative bubble but also of fraud through the circumvention of the regulator.
TODAY 9 BILLION BOTS, TOMORROW 7 BILLION BTP
The short financial week in Piazza Affari will be dominated by Treasury auctions, the first to be settled in 2018. Today the ministry will offer six-month BOTs for 6,5 billion and Ctz for 2,5 billion. Tomorrow will be the turn of the medium-long term auction: between 5 and 7 billion spread over five-year BTPs, two ten-year bonds (June 2027 and August 2027) and CctEu.
IN 2018 SUPPLY DECREASE (-30 BILLION)
In the afternoon of the 22nd, the public debt management guidelines came out, the last ones signed by Maria Cannata who in February she will leave as director of the Treasury Department.
In 2018, the demand for debt will decrease by 30 billion (184 billion excluding Treasury bonds) but the net supply will be positive in the extra-long segment, given the absence of maturities of securities from 15 years upwards. The goal is to bring the average duration of the debt, currently 6,9 years, to 7 years. Next year there will be at least one BTP Italia issue with a 6-year maturity.
CHRISTMAS YELLOW FOR THE EURO. SWORD OF DAMOCLE ON ILVA
In the eurozone, the most important appointments, scheduled for Friday, concern inflation data from Germany and Spain.
On the 24th on Wall Street the euro was quoted for a few minutes at 1,1558 against the dollar, only to then correct to 1,1870. The flurry was apparently caused by the incorrect entry of electronic orders on a day of very little trading.
Always hot, outside Piazza Affari, the Ilva question. The Reuters agency reports that Arcelor Mittal has requested the revision of the contract of last June to expressly provide for "judicial risk" as a cause of nullity.
In the eurozone, the most important appointments, scheduled for Friday, concern inflation data from Germany and Spain.