Volatile session for the European stock exchanges, with the ECB leaving the lists rather cold and Wall Street struggling to find a direction in the first hours of trading. The closure of the continental markets was mixed, while the euro appreciated against the dollar (to 1,187, after a surge above 1,19) and the pound (0,92).
Piazza Affari is the only one with a slight increase, +0,25%, thanks to the purchases of banks and Fiat (+2,85%), which offset the sales of Atlantia (-2,61%), pharmaceuticals and utilities. There is a modest decrease in Frankfurt -0,23%, Paris -0,38, Madrid -0,31%, London -018%.
So Christine Lagarde it does not overwhelm the markets: confirms Frankfurt's ultra-accommodative policy, improves economic estimates for the area, but remains cautious on the hot topic of exchange rates: ”The Governing Council has discussed the appreciation of the euro but the exchange rate is not a target of the our monetary policy”, even if the ECB will monitor the situation with regards to the effects on inflation “carefully”.
On the US front, however, positive winds seemed to be blowing again today, with the Nasdaq ready for a new, strong recovery despite the fact that the data on weekly unemployment claims had turned out to be worse than expected. Then the price lists began to slow down, they went red and are now back in positive territory, but not far from parity. The most obvious change of pace is that of Apple, which has gone from strong purchases to a slight decline. As for the chicest battle, the one between Lvmh and Tiffany (both moderately positive in Paris and New York), there is a countersuit by the French against the American queen of jewels, which would show post-Covid accounts, no longer adequate for the marriage announced.
Again on the subject of precious metals, purchases of gold continue: spot gold is up by 0,57% to 1957,7 dollars an ounce. On the other hand, oil returned to the red and Brent dropped 0,7%, trading at 40,5 dollars a barrel.
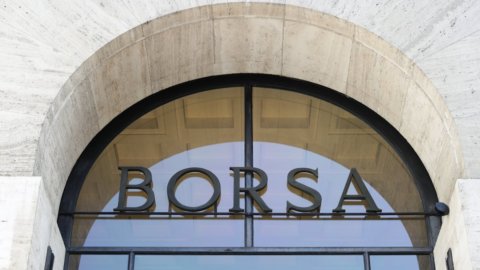
The main list of Piazza Affari is dominated today by Banco Bpm, +7,24%, on which appetite is rekindled in a perspective of recovery of banking risk. Mediobanca also did well +4,14%, Bper +2,57%, Unicredit +1,28%; Understanding +0,61%. The latter, writes Reuters, has joined the consortium formed by the French stock exchange operator Euronext and Cassa depositi e prestiti to propose a joint offer for Borsa Italiana in view of the deadline set for tomorrow. The indiscretion comes after the minister Roberto Gualtieri had a conversation on the future of Borsa Italiana with the CEO of Euronext, Stephane Boujinah.
Effervescent Nexi, +6,81%, thanks to the perspective of a impending merger with Sia and the government's plan to encourage the use of electronic payments.
In evidence Fiat, after the confirmation of the Bofa buy and the day after the presentation of the new Maserati. The CEO of FCA, Mike Manley, also confirmed that the merger work with PSA is proceeding well.
At the bottom of the Atlantia list, based on rumors that negotiations with Cassa Depositi e Prestiti on the future of Autostrade per l'Italia are once again uphill.
Forgiveness A2a -1,71%; Exor -1,65%, Recordati -1,24%, Snam -1,37%. The ECB's policy reassures the secondary sector. The spread between Italian and German ten-year bonds fell to 145 basis points (-2,9%) and the BTP rate closed at 1,02%.