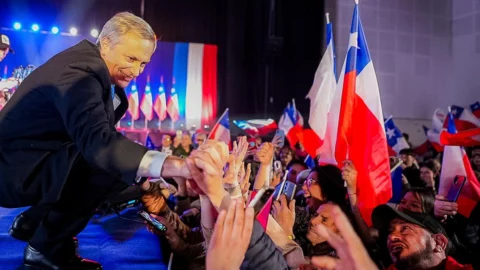
Chile, governed since last March by “Trumpian” turboliberalist José Antonio Kast, is becoming a major beneficiary of international portfolio rotation out of the United States. Non-resident investors' holdings of Chilean sovereign bonds denominated in pesos increased by $700 million in August, reaching a record $21,04 billion.
Since the beginning of the year, the increase has been 42%, a rate higher than that recorded in other major Latin American markets. But behind the "Sell America" phenomenon there is also a political story. The return of foreign capital coincides with the arrival of José Antonio Kast at La Moneda and with a change of approach on economic policy.
The market's bet on Kast
Investors began to look at Chile again as soon as Kast began to gain ground in the polls in 2025. Interest then increased after his election victory in December. In July, Bloomberg reported that Foreign holdings in sovereign peso bonds had risen by $2,93 billion in a single month, at €20,2 billion, up 36% since the beginning of the year. Among the factors cited by operators were the return of a more market-friendly government and expectations of fiscal consolidation.
The central point is the promise of reduce the deficit by containing public spendingDuring the election campaign and in his first moves as president, Kast indicated a $6 billion spending cut in the first 18 months, a significant adjustment for the country. For bond investors, a reduced need for Treasury financing could translate into a smaller supply of bonds and, given the same demand, lower yields and higher prices.
From promise to market reform
The government did not limit itself to fiscal policy. In September, Kast presented a capital market reform with over 30 measures, designed to expand sources of financing for businesses and modernize the Chilean financial market, similar to what his Argentine colleague Javier Milei did with the Rigi, the Régimen de Incentivo para Grandes Inversiones, or incentive scheme for large-scale infrastructure and industrial investments. Among the interventions in Chile is the National Housing Fund, but the project more generally aims to strengthen access to credit and market depth.
Another piece of the puzzle concerns the liquidity of the bond market. The government is working on a market maker system and new possibilities for repo operations (i.e. repurchase agreements, short-term financing operations guaranteed by securities) for local pension funds, with the aim of increase trading and reduce spreads between bid and ask pricesThese are technical measures, but they are relevant for foreign investors: a more liquid market reduces one of the implicit costs of entering and exiting positions.
Government claims bond record
At the Chile Day in Madrid, Minister of Economy and Mines Daniel Mas presented Chile as a once again competitive destination for foreign investments, citing progress on the fiscal front, regulatory simplification, and investment promotion. For the period 2026-2029, the government estimates investments of $95,1 billion, 74% of which will be attributable to foreign capital. It is therefore correct to speak of a "Kast effect" perceived by the markets.
The copper factor completes the picture
But politics is not the only explanation. Chile also benefits from rising copper prices, a crucial variable for the country's public finances, economic performance, and trade balance. Increased revenues from the mining sector, combined with reduced spending, could reduce the government's financing needs. This is one of the reasons why operators see room for a reduction in financing costs.
The result is a combination that the market is watching closely: less concentration on American assets, favorable raw materials and a Chilean economic policy oriented towards fiscal consolidation and market liberalization.
A trend that is not yet structural
The record number of bonds held by foreigners does not, however, mean that global capital has definitively chosen Santiago as an alternative. Flows remain sensitive to the dollar, to Federal Reserve decisions, the price of copper, and the government's ability to translate fiscal promises into concrete results. For now, however, the signal is clear. International capital is returning to Chilean debt just as the new government is trying to reposition the country as an investment-friendly market.
The investors' bet, rather than on Kast as a person, seems to be on combination of fiscal discipline, market reforms and fundamentals of Chile. And it is this combination that is driving the peso-denominated debt to a new record of international interest.