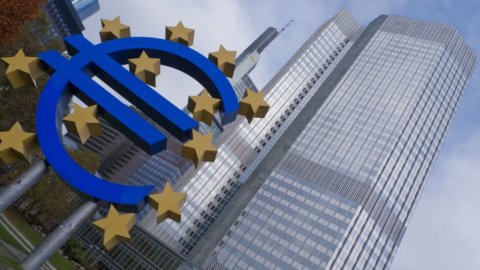
After an opening to lights and shadows the European stock exchanges they take the path of increases on a day dominated by politics from one side of the ocean to the other. But the wait is above all for the ECB which according to analysts in the early afternoon will almost certainly leave rates unchanged and provide some veiled indications on the next moves. “Lagarde will leave other doors open by continuing to emphasize the data-dependent nature of the ECB, which makes it premature to give more decisive signals on future meetings,” Jan von Gerich, an economist at Nordea, told Reuters, while Reinhard Cluse, an economist at UBS, said added: “According to our main scenario, the next ECB rate cut will take place in September and will be followed by a long and gradual sequence of rate cuts of 25 basis points per quarter in December, March, June and so on, i.e. in months in which the new macro projections will be presented".
In the meantime, the Fed Beige Book, in which the central bank defined US economic growth as "weak to modest", strengthening the hypothesis of an initial short-term rate cut.
From Trump and Biden to von der Leyen: The stock markets look to politics
Strasburg, Milwaukee, Washington. If investors had three eyes, each of them would be turned towards one of these three cities.
In Europe, after keynote speech this morning, the attention of the price lists is concentrated on the vote for the possible encore of Ursula von der Leyen at the helm of the EU Commission. The outgoing president has already obtained the approval of the Popolari, Socialists, Liberals and Greens, while the vote of the ERC Conservatives led by Prime Minister Giorgia Meloni is still in doubt.
In the meantime, the wait for the speech that Donald Trump will be held this evening in Wisconsin at the Republican Convention which has already crowned him as the GOP's official candidate for the November presidential elections. A wait that became almost spasmodic after stock market collapse of chip manufacturers. Colossi like TSMC – the world's largest contract chip manufacturer – and Nvidia went Ko after that in an interview with Bloomberg Businessweek the former president said Taiwan should pay the United States for its defense as it gives the country nothing. In parallel, the Biden administration reported Bloomberg News, instead told allies it is considering strong restrictions if companies like Tokyo electron e ASML continue to grant China access to advanced semiconductor technology. The United States is also considering additional sanctions on specific Chinese chip companies linked to Huawei.
Chapter Biden: The president of the United States tested positive for Covid-19 and was forced to interrupt his election campaign in Las Vegas, Nevada. The White House reassured the public about his health, but what happened fueled new speculation about his possible withdrawal from the race for the White House. According to sources cited by CNN, Biden has appeared open to discussions about his political fate, posing the question to his advisors as to whether Kamala Harris might be capable of winning the election.
European stocks rise mid-day
With so many irons in the fire, the European stock exchanges they proceed upwards, with the Stoxx 600 which gained 0,46% thanks to purchases in the energy sector which offset the declines in tech stocks.
The best is London, which marks +0,78%. Positive too Madrid, Amsterdam and Paris, all three with increases of more than 0,6%, while it is traveling further back Frankfurt (+ 0,23%).
In this context it is toned Milan which gains 0,64% to 34.598 basis points.
In Piazza Affari purchases of cars and oil
The automotive sector is driving the Ftse Mib, with Iveco (+ 4,17%) and Stellantis (+2,61%) at the top after Acea data according to which in the month of June, 1.310.989 new cars were registered in Europe (EU+EFTA+UK), up 3,6% compared to the same month of 2023. In the European Union alone there were 1.089.925 registrations, an increase of 4,3 percent. Positive too Ferrari (+0,8%).
Energy purchases: A2a (+ 1,04%), Eni (+0,89%). The financials are opposed: Finecobank (+0,9%), Intesa Sanpaolo (+0,84%), nexi (+ 0,82%), Pop Sondrio (-0,56%), Banca Mediolanum (-0,18%).
At the bottom of the list there is instead Prysmian, which lost 2,27% despite Berenberg's promotion which raised the target price on the company to 75 euros per share from the previous 63 euros and confirmed the "Buy" recommendation on the stock.
Chip weakness weighs on stmicroelectronics (-0,74%), bad too Interpump (-0,4%).
Out of the main basket, it flies Acrobatic construction +12,9%, which recorded a 40% growth in contracts in the first half of 2024 and in customers (+59%).
Unieuro close to takeover price
After Wednesday's race, eyes are still focused on Unieuro, which lost 0,5% to 11,54 euros. The stock is however close to the price of theTakeover bid launched by the retail sales group Fnac Darty. This is a mixed takeover offer presented jointly with Ruby Equity Investment which provides for a valuation of Unieuro equal to 12 euros per share, with a premium of 42% compared to the closing price on 15 July. The share can be paid with 9 euros in cash and 0,1 Fnac Darty shares (therefore, for every 10 Unieuro shares tendered to the offer, 90 euros and one newly issued Fnac-Darty share will be paid). The operation should be closed by the fourth quarter of 2024 and the goal is to create a group with over 10 billion euros in turnover and almost 30.000 employees.
Spreads rising, focus on bitcoin and gold
On the secondary side, waiting for the ECB spread it is at 130 basis points, one point higher than yesterday's closing, while the yield on the benchmark 3,72-year BTP is stable at XNUMX%.
The exchange rate hasn't changed much euro/dollar, which moves to 1,092, while the Petroleum is essentially stable after the larger-than-expected decline in crude oil inventories in the United States, the world's largest oil consumer. Brent changes hands at 85 dollars a barrel, WTI at 82,93 dollars.
After the rush of the previous sessions the Bitcoin it moves away from 65 thousand dollars and stands at 64.528 dollars. New highs for their with the contract for August delivery at $2.469,40, up 0,39%. The spot contract also rose, up 0,2% to $2.464 an ounce.