

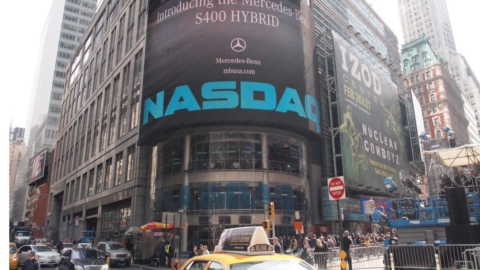
La United States Stock Exchange rediscovers today what had been the main theme for months, before the July break, Artificial Intelligence: Nasdaq + 3 %. S&P500 +1,6%. Sector rotation leaves behind the Dow Jones +0,3% and Russell 2000 +0,6%. The index Sox of chip companies earns the 5%: to find such a variation you have to go back to February.
Salt on Nikkei +0,2% after the announcement of the decisions of the Central Bank of Japan. The JPY it reaches three-month highs. It is heading towards the best month since November 2023 with +5% thanks to the dismantling of historic carry trade positions. There Central Bank increased its short-term reference rate by 15 basis points to about 0,25%, the upper limit of market expectations, but he also said he would halve the pace of bond buying.
Stock market August 1st: the Fed opens the door to the September cut
Yesterday, as expected, the Federal Reserve lowered interest rates unchanged at 5,25-5,50%, but met analysts' expectations, paving the way for the September cut. “A reduction in the key rate could be on the table as early as the next meeting in September,” the Fed president said Jerome Powell during the usual post-meeting press conference. “We are getting closer to the point where it will be appropriate to reduce our policy rate, but we are not there yet.”
Stock Market August 1st: AI champions awaken
Meanwhile, the champions of theArtificial intelligence, starting from Nvidia +12,8% from -7% the previous day, after that ecosystem has provided the latest indications on the colossal scale of investments in Artificial Intelligence.
Reduces Microsoft losses -1%. The software giant closes the fourth quarter of the fiscal year with revenues rising by 15% to 64,73 billion dollars, above the expectations of analysts who were betting on 64,52 billion. Net profit increased by 10% to 22 billion. Revenues from the Cloud division amounted to 36,8 billion, less than the 36,84 billion expected by the market.
Intel +2%, plans to cut thousands of jobs in the coming months, he writes Bloomberg. The announcement could come today or in the next few days. The CEO Pat Gelsinger intends to save on personnel costs in order to have the resources to allocate to relaunching the business.
Advanced Micro Devices +4,3% The chipmaker gave an upbeat revenue forecast, noting that its new AI processors are boosting growth. Revenue will be approximately $6,7 billion in the third quarter. Second quarter results also came in ahead of expectations.
Contrasted European stock exchanges
European stock markets contrasted. The month is about to close with a slight decline (-0,4%). European banks are taking off thanks to an excellent quarterly reporting season. The index Stoxx Banks yesterday it reached a level not seen for nine years. The 2024 performance grows to +22%, the best result at a sector level. In second place, far behind Pharmaceuticals (15,5%). The Stoxx 600 index is stuck at +7,4%.
Much of the credit for the rally can be attributed to the Italian banks. The index Ftse Italia Banks rose to the highest since 2011, extending the 2024 performance to +46,50%. The FtseMib index is stuck at +12%. Intesa Sanpaolo slows down -1,6% JP Morgan raises the target price to 4,40 euros. Estimates of net profit for the entire year are rising, now seen at "over 8,5 billion" from "over 8 billion" previously.
FtseMib -0,4%, +1,7% per month. CAC40 of Paris +0,76%, +0,7% on the month.
In July, retail and large-scale distribution companies rose in Europe, Stoxx +6%. Bad this month the tech -5,3%. But it bounces Asml +5%. Second Reuters, the new US regulation on exports of chip equipment to China exempts the Dutch manufacturer from tariffs.
A Business Square marks the pace Tim -1,7% Fitch raises the rating to BB, due to the sale of the network. Slows Intesa Sanpaolo -1,2% Jp Morgan raises the target price to 4,40 euros. In terms of performance, in 2024 there are four Italian stocks among the top ten places of the Stoxx Banks index: Bper + 81% Ps + 65% Unicredit + 56% Understanding + 44%.
Gold goes up: 0,3% at the opening after +1,1% yesterday. The market positions itself before the appointments with the central banks, starting with the Fed. Le growing geopolitical tensions (Ukraine, Middle East, Venezuela) as well as the decline in yields of bond favored the resumption of purchases.
(Last update: 11.21am on 1 August).



