There is no peace for the Federal Reserve (Fed) under the second mandate of Donald TrumpAfter his reinstatement to the White House last year, the tycoon returned to targeting the federal government's top financial institution. The problems had already begun during his first term, when The Donald criticized the then chairman of the Fed Board, Jerome Powell, who Trump himself had appointed to the position in 2018.
The growth of the US economy before the onset of the pandemic COVID-19 in 2020 had induced the Fed to raise the interest rates, but the tycoon would have liked them to remain low. The controversy then flared up again with the second administration of The Donald as a consequence of the increase in the cost of living that Trump had inherited from his predecessor, Joe Biden.
Trump renewed his attacks on Powell, even accusing him of attempting to hinder inflation by refusing to cut interest rates. Faced with Powell's resistance to pressure from the White House to either bend to his will or resign, The Donald instructed the Justice Department to launch a criminal investigation into the Fed chairman's actions. Powell was charged with perjury for statements he made during a congressional hearing regarding funding for the renovation of the Fed's headquarters.
Trump was looking for a pretext to remove Powell, as his removal without just cause would be unlawful in the name ofindependence of the Fed from the executive power.
In parallel, the tycoon attempted to remove from office one of the members of the Board of seven governors of the Fed, Lisa Cook, who had been appointed by Biden. The Donald attributed Cook to alleged fraud in obtaining a mortgage on favorable terms.
However, the judiciary has undermined Trump's strategy. Last 29nd June The Supreme Court blocked him from removing Cook, arguing that he could retain his seat on the Board while the litigation over the alleged mortgage irregularities was ongoing.
Previously, the judge James E. Boasberg, of the Federal District Court for the District of Columbia, had induced the Justice Department to close the investigation into Powell because the magistrate had dismissed the charges against him as a mere pretext used by the White House with the sole purpose of undermining Powell in an attempt to influence the Fed's monetary policy.
From Powell to Warsh
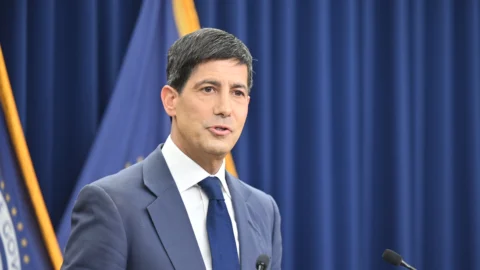
Powell was thus able to regularly conclude his mandate on 15st May last. In his place Trump nominated, and the Senate confirmed, Kevin Warsh. Since the previous January, the tycoon had indicated Warsh as the successor to Powell, who at the time was still under investigation, with the explicit expectation that he would implement a more expansionary monetary policy.
One of Warsh's main sponsors was the Secretary of the Treasury, Scott BessentWith his support, Bessent may have also wanted to repay a debt to Warsh, who had been the tycoon's first choice – later abandoned – to lead the Treasury Department. In any case, with Warsh's appointment, the past conflicts between the Fed and the Trump administration seemed destined to be smoothed over, given that the new president was a figure favored by both the White House and the Treasury Secretary. Instead, the conflict reignited and, this time, pitted the Fed against the Trump administration. Fed directly to Tesoro. Once again the controversy is over the level of interest rates.
All 'Economic Policy Symposium in Jackson Hole At the end of August, Warsh opened the door to their increase, due to the presence of ainflation at 3,7% and therefore far from the target of the 2%.
Trump, who previously admitted making a mistake in appointing Powell, can't admit to making another with his choice of Warsh. He thus left it to Bessent to criticize Warsh, arguing that the Fed shouldn't rush to raise rates but would be better off waiting to calmly assess whether rising energy prices have led to a stable, rather than temporary, increase in the prices of other goods and services.
The Fed's Aspiration for Full Independence
The conflicts between the Fed and the Treasury are nothing new since the former was formally made independent from the federal government. Established in 1913, the Fed was conceived as an agency to supervise the entire banking system and determine monetary policies through the interest rate charged on money lent to requesting banks. Until the enactment of the Bank Act of the 1935 there was a de facto subordination of the Fed to the executive branch, as the Secretary of the Treasury was ex officio also the Chairman of the Board of the Fed.
Furthermore, the latter was also a member of the Comptroller of the Currency, a federal official appointed by the White House who heads the agency, subordinate to the Treasury Department, which oversees the circulation of currency. Therefore, monetary policies ended up reflecting the White House's orientation.
For example, the Fed agreed that all its gold reserves would be transferred to the Treasury following the enactment of the Gold Reserve Act il On 30 January 1934. Instead, the departure of the Secretary of the Treasury and the Comptroller of the Currency from the Board in 1935 created the conditions for a potential confrontation between the Fed and the federal government, for whose strategy the department is the spokesperson.
However, national emergencies such as the protracted economic depression of the 1930s and the Second World War contributed to stifling the divergences during the years in which the Board was chaired by Marriner S. Eccles (1934-1948). In particular, to help finance the US war machine during the war, the Fed kept interest rates low and, in particular, set the 2,5 % the yield on long-term government bonds.
In other words, the Fed's monetary policy was set to meet the needs of the Treasury, which needed access to cheap credit to pay for Washington's military spending.
Thomas B. McCabe vs. John W. Snyder
When the Korean War broke out in June of 1950, the Secretary of the Treasury of the administration of Harry S. Truman, John W. Snyder, he expected the Fed to agree to adopt a monetary policy similar to that of the recent past. However, with inflation having reached the8%, the chairman of the Fed, Thomas B. McCabe, in office since 1948, did not want to give in to the Treasury's impositions which had instead been accepted, even though reluctantly, from Eccles. McCabe's resistance – who was significantly supported by Eccles, who remained on the Fed Board until 14 July 1951 after leaving the presidency – provoked a tug-of-war with Snyder.
The dispute ended on March 4, 1951 with the release of a joint press release. The essence of the agreement was that, from then on, the Fed would be able to formulate monetary policy solely on the basis of macroeconomic conditions, rather than to meet the Treasury's needs.
It was also a way for the Fed to try to curb the growth of federal debt. However, McCabe resigned a few days later and Truman replaced him with William McChesney Martin, the acting assistant secretary of the Treasury, an appointment that effectively placed a man from the department at the helm of the Fed.
Arthur F. Burns vs. John B. Connally
The disagreements of recent years bear similarities to the tensions between the Fed chairman Arthur F. Burns e John Connally, the Republican Treasury Secretary Richard M. Nixon between the 1971 and the 1972.
Burns, like Powell and Warsh, had been appointed in 1970 by the tenant of the White House, from whose choices he soon found himself diverging. The economic context was one of high inflation, the 5,7 % in the summer of 1970, although well above today's level. Burns had deep reservations about the revocation of the dollar's gold convertibility, which marked the abandonment of the system of Bretton Woods, decided on August 15, 1971 by Nixon, on Connally's advice to inflate the dollar and revive the economy through an increase in exports, favored by the depreciation of the US currency.
Furthermore, like Powell and Warsh, Burns was pressured to keep interest rates low, also for electoral reasons: today the vote of midterm neighbor November 3, then the 1972 presidential elections, in which Nixon aspired to obtain a second term.
Nixon was convinced he had lost the race for the White House against the Democrat John F. Kennedy in 1960 due to a recession he attributed to the Fed's interest rate hike in late 1959. To prevent this situation from recurring in 1972, Nixon persuaded Connally to pressure Burns to adopt a monetary policy consistent with his electoral aspirations. However, it was not so much the Treasury Secretary's attempts to pressure Burns that forced him to give in, but rather a press campaign against Burns, fomented anonymously by the Nixon administration, and the threat of introducing a bill in Congress to reduce the powers of the Fed Board.
From G. William Miller to Paul A. Volcker
Burns' successor as Fed chief, G. William Miller, chosen by the Democrat Jimmy Carter in 1978, he had no easier relationship than his predecessor with the Secretary of the Treasury at the time, W. Michael Blumenthal, who had also encouraged his nomination by the White House.
Once again the crux of the matter was the question of the interest rates. In a context of stagflation, that is, the coexistence of economic stagnation and inflation, Miller was reluctant to raise rates, convinced that they would not serve to contain inflation and would instead interfere with the economic recovery and the reabsorption of unemployment.
Blumenthal, however, held the opposite view. In his view, maintaining low interest rates would cause the economy to grow excessively rapidly, which would quickly plunge the United States into recession. Carter temporarily healed the rift between the Fed and the Treasury when, as part of a cabinet reshuffle in July 1979, he asked Blumenthal to resign and replaced him with Miller.
However, the conflict between the two institutions was rekindled by the new president of the Fed, Paul A. VolckerThe latter's decision to adopt a deflationary policy, bringing the discount rate to 14,5 % in October of the same year, it was an open repudiation of Miller's strategy and determined a Copernican revolution in the objectives of federal intervention in the economy: no longer the creation of jobs, as had happened since the 1930s with the New Deal, but the containment of inflation.
Volcker's policy also marked an affirmation of the Fed's independence from the Treasury, precisely because Miller was convinced that such a strategy would have damaged businesses, the world from which he himself came as a former CEO of the Textron, an aviation conglomerate, and hurt Carter's re-election chances in 1980.
But the leeway Volcker gained in the fall of 1979 was short-lived. He himself reported in his memoirs that he had been summoned to the White House in July 1984 where, James baker, the Republican's chief of staff Ronald Reagan, bluntly, he ordered him: “the president orders you not to raise interest rates before the elections” (Keeping at It: The Quest for Sound Money and Good Government, New York, PublicAffairs, 2018).
The possible future of relations between the Fed and the Treasury
Beyond the contingent factors that have historically caused them, the contrasts between the Fed and Tesoro they are part of a dialectic of the former's claim for autonomy and the latter's search for control, or at least influence, of monetary policies.
The opposition has intensified with the Trump administration, mainly in light of the tycoon's claim to subordinate all federal agencies and institutions to his will on the basis of the principle of“unitary executive”, a controversial interpretation of the first paragraph of Section I of Article II of the Federal Constitution that would grant the President total control over the entire federal administration, including formally independent agencies.
Nonetheless, in the case of the Fed, this isn't just an institutional clash, and its scope seems to transcend the interest rate debate. The Fed, in fact, isn't just concerned with monetary policy; from its inception, it has also, and above all, overseen the operations of banks.
One might thus suspect the White House, through the Treasury Department, of intending to reduce the Fed's oversight role, especially given the clear conflicts of interest of Trump and his entourage in the financial field, as a result of a veritable monetization of the federal presidency.
It would be enough to think about the fact that, as recalled by the authoritative British newspaper "The Guardian" a few weeks ago, over the course of 2025 the tycoon would have earned approximately 1,4 billion dollars thanks to the companies linked to his family that operate in the field of cryptocurrency, in the face of quantifiable losses for investors estimated in the order of 3,8 billion dollars (Peter Stone, Trump has amassed staggering wealth in “most openly corrupt” presidency, 13 August 2026).
It goes without saying that the low cost of money incentivizes the pursuit of higher returns in high-risk sectors, such as cryptocurrencies. In any case, the combination of Warsh's substantial silence on the Fed's regulatory interventions and his openness to raising interest rates would suggest a theoretical compromise solution that would see the Fed retain control of monetary policy in exchange for a certain laxity in the use of its regulatory functions.
Maybe it's just fantasy politicsBut with Trump we have become accustomed to situations in which reality has often surpassed fiction.