

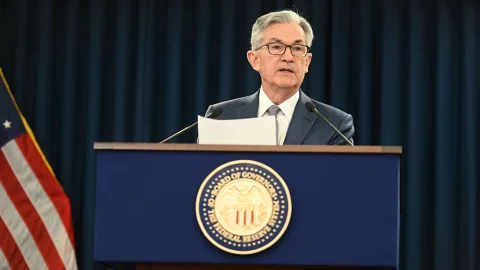
Of all the numerous news that have crossed the markets in the last few hours, investors have chosen, at least for now, to highlight the statements of the Chairman of the Federal Reserve Jerome Powell yesterday, which gave us a glimpse of further rate cuts on the horizon. The other issues that have tormented investors in recent days have therefore been set aside for now: from the continuous mutual challenges between USA and China, with a latest episode that saw the clash between Chinese cooking oil and soy, at political tensions both in Japan both in FranceThe air of rate cuts has brought down the dollar, making it more convenient to purchase , climbed to new records over $4.100 an ounceA wave of optimism has returned to the stock markets, pushing Asian markets higher, and European markets are also pointing to a sharply higher opening. Middle East, According to the latest reports, Hamas has handed over four more bodies and said it is willing to release heavy weapons. Israel will reopen the Rafah crossing today, allowing humanitarian aid into the Strip.
Yesterday on Wall Street the Dow and Russell 2000 closed higher
Yesterday the Dow on Wall Street closed higher, while the S&P 500 and the Nasdaq closed the session in negative territory with investors having to weigh up the optimism of the International Monetary Fund and of the president of the Federal Reserve Jerome Powell regarding the economy, on the other hand the new trade tensions between United States and China. Stocks lost momentum late in the session after U.S. President Donald Trump Trump He wrote on social media that he was considering ending some trade ties with China.
The industrial average of Dow Jones has closed rising by 0,44%, to 46.270,46, while the S&P 500 fell by 0,16% to 6.644,31 and the Nasdaq Composite fell 0,76% to 22.521,70. Mid- and small-cap companies also rose, the index Russell 2000 +1,2%.
Powell He said the U.S. economy as a whole “may be on a somewhat stronger trajectory than expected,” though he cautioned that “there is no risk-free policy path as we navigate the tension between our employment and inflation targets.” This echoed a report by IMF which raised its global growth outlook, as, it said, tariff shocks and financial conditions had proven more favorable than expected. However, the IMF warned that the trade war between the world's two largest economies could significantly slow production. These indications left the door open to a monetary easing, which, according to futures, could even be 50 basis points within the year. The first meeting of the FOMC Fed will be held next October 29th.
- United States and China continue to exchange threats and retaliations on the commercial level: in the latest episode the clash was oncooking oil and soybeans.
The quarterly results of JPMorgan, Wells Fargo, Citigroup and Goldman Sachs, who kicked off the season, have tested positive. Today it will be the turn of Bank of America and Morgan Stanley.
This morning i Nasdaq futures gained 0,31%, while S&P 500 futures advanced 0,26%.
The US and China clash over oil and soybeans. China strengthens the yuan.
Continue on arm wrestling between China and the United States in trade relations. After the mutual retaliation yesterday in the maritime area, the latest episode concerns the threat of a embargo on Chinese oil arrived last night from Donald Trump, in retaliation for the boycott of the soybean. However, the announcement was not taken too seriously by the markets, especially since the United States Trade Representative, Jamieson Greer stated at the Cnbc that the presidents Trump and Xi Jinping are ready to meet.
The air of interest rate cuts, which came after the words of Powell Yesterday, the MSCI Asia Pacific Index gained 1,3%, its first gain after three sessions of decline. Hong Kong's Hang Seng Index rose 1%, a rebound after a decline of about 7% over the previous seven sessions. China Life Insurance gained 4%, Alibaba 2%. The CSI 300 index of the Shanghai and Shenzhen stock exchanges was at par. Taipei's Taiex index rose 1,2%.
La China ha raised its guard on its currency, with the authorities having set the yuan's reference rate at 7.0995 per dollar, below the 7.1 threshold. This is the first time since last November that the central bank has set a stronger value. Analysts interpret the decision as a signal of strength sent by Beijing to the United StatesThe yuan has already risen more than 2% this year, without the economy feeling the pinch. Strategists at JP Morgan Asset Management, Gathering in Seoul for the first Asian media summit, they said Asian markets continue to hold strong appeal for investors: they have demonstrated resilience in the face of global economic headwinds, including tariffs and geopolitical tensions, thanks to a combination of strong domestic revenues, robust technology sectors, and a more moderate investment climate toward U.S. assets, JP Morgan said. According to today's data, producer prices in China fell 2,3% from the previous year, the 36th consecutive month of decline, in line with forecasts. deflation Manufacturers' inflation eased for the second consecutive month, though it remained unchanged at zero on a monthly basis. Pressured by falling food costs, consumer prices fell 0,3%, while the core consumer price index, which excludes volatile items like food and energy, rose to 1%, a 19-month high.
The Nikkei Stock Exchange Index Tokyo is up 1,2% and the yen strengthened against the dollar to 151,2, from 152 yesterday. Political tensions remain high in Japan, as minority parties rejected the ruling coalition's proposal to vote on October 21st to choose the next prime minister, local media reported Wednesday, prolonging uncertainty over Sanae Takaichi's candidacy to become the country's first female prime minister. The stock market South Korea is rising sharply, Kospi index +2%, towards a close at record levels.
Il dollar, on Fed rate cut bets, fell 0,4% against the yen to 151,23 and 0,16% against the Swiss franc at 0,8000. Slight increase for theeuro at 1,1611 dollars and for the GBP 1,3349 dollars.
The spot gold extended its record run and rose 0,9% to $4.178,49 an ounce. Prices of Petroleum fell, with Brent crude futures falling 0,37% to $62,16 a barrel, while U.S. crude fell 0,31% to $58,52 a barrel.
European stocks opened strongly. At the Milan Stock Exchange, Stellantis and Eni were all eyes on the stock.
European markets are expected to open higher, with Euro Stoxx 50 futures up 1,2%.
FranceAll eyes will be on what happens to the government after French Prime Minister Sebastien Lecornu promised to suspend a landmark pension reform until after the 2027 elections.
ItalyThe BTP strengthened with its yield falling to 3,39%, the lowest level since last December, while waiting for the Treasury to announce the coupons on Friday. BTP Value.
Asml holding Samsung Electronics Co. Ltd. (SIX: SIX) released third-quarter sales of €7,5 billion, below estimates of €7,7 billion, while orders exceeded expectations. The Dutch semiconductor equipment manufacturer recorded bookings of €5,4 billion, compared to analysts' expectations of €4,9 billion. The company expects sales next year to be at least in line with 2025, thanks to growing demand for AI-powered chipmaking equipment.
Banks and Insurance The government will raise funds to finance the budget from banks and insurance companies. The budget is estimated at €4,5-5 billion. The Ministry of Economy and Finance announced this after the Council of Ministers meeting, during which the Draft Budgetary Document (DBP) was presented.
Eni – BNP Paribas Exane raised its target price to 14,5 euros, from 13,5 euros previously.
Stellantis – It announced a $13 billion investment plan over the next four years to support its U.S. operations and increase production by 50%.
Snam - Second ReutersSpanish operator Enagás is in talks to acquire the 32% stake held by Singaporean sovereign fund GIC in Teréga, France's second-largest gas transmission operator, of which Snam owns 40,5%.
Telecommunications Bouygues Telecom, Free-iliad Group, and Orange have submitted a joint, non-binding offer to acquire certain Altice assets in France, valued at a total of €17 billion.
Tenaris – Oddo lowers the target price to 12,5 euros, from 13,5 euros previously.
Unicredit – Equita raised its target price to 71,5 euros.



