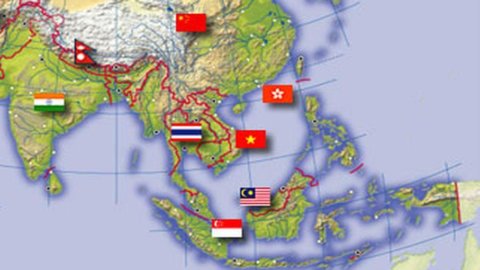
Economic growth, fiscal strength, bank reliability and foreign exchange reserves. These are the main reasons, according to the analysis of Schroders, a global asset management company founded in 1804 and listed on the London Stock Exchange, to invest in Asia. Schroders has 32 offices in 25 countries, primarily in the Asia-Pacific region, and operates a total assets of $328,7 billion globally.
Of this sum, 82,8 billion are managed precisely in the Asia-Pacific area, of which 17,3 billion in Japan, 11,6 in Hong Kong, 8 in China and Singapore, and a good 27,6 billion dollars in Australia.
The reasons? Simple. The growth and ever greater reliability of the emerging markets of the Orient is no longer a secret, and is even more supported by some data. For example, fiscal strength: the fiscal balance, as a percentage of GDP, in 2011 shows only two countries with a positive figure, which are Hong Kong and South Korea, with around 2%. Slightly below 0% are Indonesia and China, while the only competitive European country in this respect is Germany with -1% (Italy is at -4%, France at -6, not to mention of Ireland and Greece over -10%).
Furthermore, these Asian states are the only ones to have a gross public debt, as a percentage of GDP, less than or equal to 50%: Hong Kong, Korea, China, Indonesia, Thailand and the Philippines, with Malaysia and India slightly ahead and only Japan flying over 200%. The average of Western countries is around 100% represented by the United States, while Italy reaches 120%.
The Asian continent, excluding Japan which is a much more mature economy and already too exposed to the debt crisis, is the only one that can boast positive gross domestic product growth forecasts between now and 2013 (and already since 2009, the year of the global financial crisis): in 2012 the area average is around +6,5%, while the USA will grow by only 2%, Japan by 1 and Europe will even decrease overall about 0,5%. Latin America is keeping up with +3,8%, but forecasts for 2013 hold it steady at +4% while Asia-Pacific according to Thomson Reuters estimates will return to travel above +7%.
Between now and 2020, according to HSBC data, the three countries that will improve their GDP the most are Malaysia, China and India, which will also see, together with Turkey, Russia and Poland, the greatest growth in per capita wealth.
To date, however, Asia is still underrepresented in global bond indices: according to Bloomberg data, only 8% of public debt securities outstanding are from the eastern continent. Just over double that of the UK alone and a third that of Europe. In the HSBC Asian Local Bond index, the most represented country is Korea with 16,6% (3,77-year yield 14,9%), Singapore with 1,54% (rate 13%), Indonesia with 5,34% (rate 12,6%) and Hong Kong with 10% (yield 1,32 years at XNUMX%).
Yet the Asian bond universe is predominantly composed of Highly rated countries: Singapore and Hong Kong are triple A by Standard & Poor's, while Taiwan, China, South Korea, Malaysia and Thailand are in band A with both S&P's and Moody's. And the Asian bond universe has delivered particularly solid results over the past seven years, with bond and currency yields having tripled since 2005 in some cases, such as the Philippines and Indonesia.
According to Schroders, in intersecting data on growth and investment prospects in the markets, the opinion remains positive in the medium term, even if the global uncertainty calls for prudence. In particular, the negative trend of the US dollar should continue in the medium term, due to the US fiscal problems, and the strong correlation with the equity markets continues to represent a risk for Asian currencies. However, the prospects for the Asian banking and corporate sectors offer encouraging signs: Asian banks are less vulnerable to deleveraging than European banks, as large foreign exchange reserves provide an additional cushion of protection. Suffice it to say that the bad debt rate of credit institutions on the continent, according to Barclays data as of December 2011, reaches a maximum of 3% in Thailand, while China is 1% and Hong Kong 0,5%. As far as corporate issuers are concerned, they are generally characterized by stable fundamentals and lower levels of debt.
Ultimately, according to Schroders, “Asian currencies remain substantially undervalued – says Rajeev De Mello, head of Fixed Income Asia -, given the greater strength of these economies. Robust and sustainable growth is driven by favorable demographic dynamics, high levels of productivity, sound public finances and effective macroeconomic policy tools. Asian bonds should also benefit from the tightening of central bank monetary policies aimed at countering inflation and the global demand for safer bond issues”. Not to mention that the yield gap between Asian bonds and those of the US, Germany and Japan marks the highest level in the last five years and that Asian corporate bonds remain attractive and continue to gain support from a robust economic backdrop, by low insolvency rates and by the general prudence of company management.