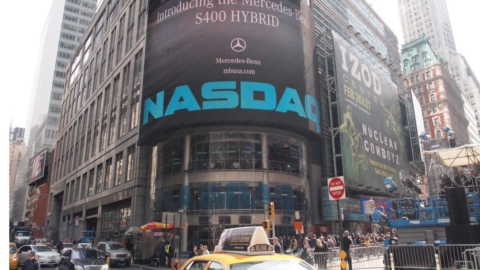
Stock markets were mixed today in Europe and the United States, as US inflation rose (albeit in line with expectations), highlighting the impact of tariffs on consumer prices in the world's largest economy. Nvidia's star continues to shine in the US stock market (+4,4%), heating up the Nasdaq and S&P 500, sending them to new highs in the first hours of trading. Europe, however, did not benefit from this euphoria, and the indices actually worsened after the opening of trading. New York Stock Exchange.
Piazza Affari thus closed at the day's low, down 0,66% to 39.921 basis points, weighed down by gains on banking stocks. Meanwhile, industrial stocks such as Stellantis (+1,14%) and Prysmian (+1,91%) regained cautious optimism, hoping for a tariff agreement between Brussels and Washington between now and August 30st, when the XNUMX% US tariff on EU goods is expected to kick in. For its part, the EU is preparing countermeasures in the event of a breakdown in trade negotiations.
In the Old Continent, Frankfurt is also weak at -0,41%, London at -0,67% (which even reached new highs of 9000 basis points during the day), Paris at -0,54% and Madrid at -1,24%, while Amsterdam is positive at +0,3% in the wake of American tech stocks.
Wall Street, led by Nvidia
Wall Street hit new records early on thanks to yet another rally Nvidia, the world's most valuable company, is celebrating the possibility of resuming sales of its H20 AI chips in China. "The U.S. government has assured Nvidia that the licenses will be granted, so we hope to begin deliveries soon," the company stated. There are also rumors of a $70 billion government plan to support the tech and energy sectors.
The performance of major banks, which kicked off earnings season today, is mixed: JPMorgan Chase is flat after above-expected numbers; Wells Fargo is in the red, weighed down by lower guidance; BlackRock is losing ground as the world's largest asset manager's quarterly revenues missed expectations (€5,42 billion, versus the consensus figure of €5,46 billion); Citigroup is up after exceeding consensus figures.
Dollar and T-Bond Prices Rise on June Inflation
On the macro front, the US inflation data was awaited with great interest, accelerating to 2,7% in June from 2,4% in May. This is an expected increase, but it also signals the effects of tariffs on consumer prices and complicates the Federal Reserve's work, at least with respect to the aspirations of easing the cost of money by Donald Trump"Consumer prices are low, lower rates now!" the US president wrote on Truth Social. Meanwhile, the Polymarket website shows that bettors are giving Trump a one-in-five chance of removing US central bank chairman Jerome Powell this year, compared to a 10% chance at this time last month.
The effects of inflation are currently being felt on the dollar, which is strengthening against major currencies, trading at three-week highs. The euro is trading around 1,163, down 0,25%. US prices are also reflecting on T-bonds, which are currently experiencing rising prices and falling rates.
Piazza Affari, profits on banks
The profits today penalize the banks of Piazza Affari with the worst being Bpm bank -2,56%, Bper -2,28% and Popolare di Sondrio -1,78%.
Unicredit drops by 1,13%, although the publication of the letter sent by the European Commission to the Italian government suggests that there is a risk of revocation of the decree relating to the Golden power applied to the Piazza Gae Aulenti offer for Piazza Meda. The problem for Unicredit is that Italy has 20 working days to submit its observations to Brussels' objections, and the deadline clashes with the offer deadline, which expires on July 23.
Meanwhile, the acceptance period for Bper's Sondrio offer will reopen on Monday, following its successful closing price of over 58% on Friday. Among the day's biggest declines were Recordati (-3,52%), Buzzi (-2,34%), and Leonardo (-1,67%).
The list of increases begins with Prysmian, which is also eyeing Nvidia and its bets on artificial intelligence. Much AI requires a lot of electricity and therefore network infrastructure, the sector in which the company operates. Cautious optimism about trade negotiations helps. Stellantis, Campari +0,92%, Interpump +0,88%.
Stable spreads
The secondary market closed stable, with the spread between 89-year BTPs and Bunds of the same maturity at 3,61 basis points, amid yields of 2,72% and 52,7%, respectively, for German bonds. The trade war is not yet threatening eurozone government bonds, and investor sentiment in Germany is also rising. The ZEW confidence index rose to 47,5 points in July, compared to XNUMX in June.