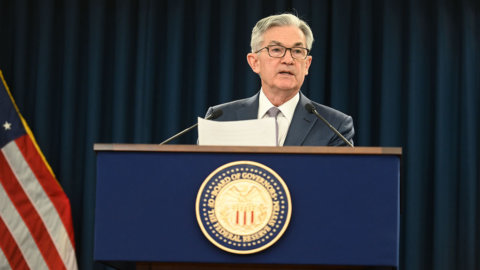
“The real question we need to ask ourselves at this point is: should we raise rates further?”. The president of the Fed Jerome Powell he takes his leave with this question after the meeting with his colleagues from the central board. Seen from the market, the joke can be interpreted as follows: a) it is not yet time to reduce rates; b) the market trend, however, justifies a pause between now and the end of the year; c) indeed, something more. The ceiling is now close, the turning point, barring new black swans, will take place by June 2024.softer attitude than expected, it already gave wings to the Bull yesterday which closed the session of Wall Street sturdy rise. The same was repeated on Asian stock markets.
The rally continues in European stock exchanges and they open all in rise. The London stock market is also in positive territory awaiting the Bank of England's rate decisions. Andrew Bailey should also avoid new increases.
Unicredit and Leonardo, new records
IERI (Yesterday) il Ftse Eb of Milan gained 0,9%, returning to almost 28 thousand points in a session with holiday tones given the public holiday. It should be noted that Unicredit has set new tops since 2016, Leonardo has set new tops since 2017, Eni e bpm they are less than two percentage points from multi-year highs.
The positive push coming from the USA is destined to involve the bond market. In the wake of the slowdown in inflation. Yesterday, before Powell's statements, prices had moved, but not too much: lo spread between 189-year BTPs and Bunds of the same duration it fell to 1,15 basis points (-4,64). The rates retreat to +2,76% and +XNUMX% respectively.
Anticipation is mounting for today's speech by Philipp Lane, the "dove" chief economist of the ECB. Among the other "price sensitive" elements of the day were the Eurozone PMI indices.
On the corporate front there is great anticipation for i accounts di Novo Nordisk, the pharma company skyrocketed by anti-obesity treatments. Also scheduled are quarterly reports from Shell and the Dutch bank Ing.
Positive Asia, rain of support for Tokyo
The charge of the Bull, which started yesterday from Wall Street, hit Asian stock markets overnight. The Asia Pacific index rose 1,6%.
Up too Tokyo +1,1%. While the cross dollar yen retreats for the second day to 150.4. Japan announced a 106 billion euro economic support plan tonight. The measure provides for a tax cut of 40.000 yen (250 euros) per taxpayer, while a further 1.000 billion yen will be allocated to return 70.000 yen to low-income families.
Kospi Index of Alone +1,7%. South Korea's inflation rate increased for the third consecutive month in October, with the consumer price index rising 3,8% year-on-year.
China's stock markets are weaker. CSI 300 of the price lists of Shanghai e Shenzen -0,1%. Hang Seng by Hong Kong d+0,9%.
Spotlight on Apple: a possible axis with Walt Disney in sport
Stock prices recovering T-bonds decennial down 18 points. This was the first reaction of the US markets yesterday to Powell's words. A response that lacks enthusiasm, according to some analysts, but which creates the right atmosphere a few hours before the key event: accounts of Apple , the first reference of US technology.
A sensational voice, also reported by Reuters, contributes to raising attention: Walt Disney could sell 20% of the ESPN network, the leading sports TV, to Apple. The objective would be to transform the TV channel into a digital TV based on streaming.
T-Bond on rally
In the meantime, the market shakes off the difficulties of October. The third consecutive rise has arrived on Wall Street: S & P 500 +1,05% to 4.237 points, Nasdaq +1,64% to 13.061 points, best session in two months.
The signs of a cooling of the labor market that emerged yesterday and the Fed's decision favored the return of purchases of loans Treasury. The US 0,65-year bond gained 4,73%, with the yield falling to 4,96%, the lowest level in two weeks; the two-year bond (5%) fell below the key threshold of XNUMX%, to its lowest level since the beginning of September.
The Treasury has communicated the calendar of bond auctions: 3-10-30 year bonds will be placed next week, for 114 billion dollars, slightly below the forecasts of market operators.
All eyes turned today to a series of US macro data to see if the economy is really sending signs of cooling: new weekly requests for unemployment benefits, estimated third quarter labor costs and productivity; review of orders for durable goods in September.
War does not heat oil
Brent at 85,40 dollars, WTI at 81,20. Prices, up 1% at the start of the session, return to yesterday morning's levels. Despite the drumbeats of Israel's enemy countries, the conflict remains limited to the Gaza Strip. JP Morgan analysts estimated that global demand for Petroleum averaged 102,1 million barrels per day (bpd) in October, about 100.000 bpd below their previous projection. Meanwhile, oil inventories rose by 0,8 million barrels to 421 million, slightly lower than analysts' expectations.
Leonardo at the top, Vivendi ultimatum on Tim
Test on the stock market for Tenaris after the accounts approved last night. The company closed the third quarter with one billion dollars in Ebitda, approximately fifty million more than consensus expectations. Sales rose 8% to $3,24 billion, in line with analysts' estimates. Net profit is about $100 million below expectations, at $545 million. The company has launched the buyback of its own shares for up to 1,2 billion, for an amount equal to 6,4% of Tenaris shares in circulation.
Eni. Chief Executive Claudio Descalzi said talks were underway with Swiss asset manager Energy Infrastructure Partners about selling part of Plenitude.
Leonardo. The treaty for the Gcap (Global Combat Air Programme) will be signed in Tokyo by the end of the year, the Ministry of Defense announced in a statement. This is a project that involves Leonardo, BAE Systems and Mitsubishi Heavy Industries.
Classic Ferrari for sale. It has no intention at the moment to move its registered office from the Netherlands, a spokesperson said after yesterday's Corriere della Sera wrote that the parent company Exor are evaluating the possibility of bringing the company's registered office back to Italy. Today the Rossa quarterly.
Tim. Vivendi has delivered a letter to the board, signed by general counsel Frédéric Crépin, in which he requests that the sale of the fixed telecommunications network receives the approval of the related parties committee and a passage to the ordinary shareholders' meeting. “Failure to do so, Vivendi will be forced to appeal to the judicial authorities”.