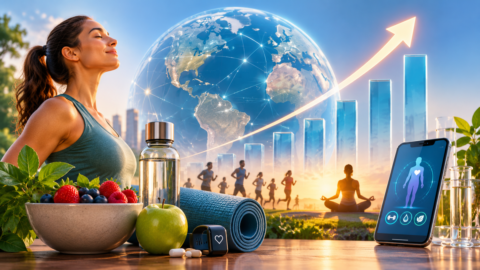
Il The global wellness market has reached a value of 2.700 trillion of dollars and is poised to play an increasingly important role in companies' growth strategies and investors' decisions. The figure emerges from theMcKinsey's latest Future of Wellness research, which captures a sector that is now much broader than the traditional gym, supplement, and personal care industry. Wellness is becoming part of consumers' daily lives and, consequently, their investment portfolios.
The $2.700 trillion figure reflects both market growth and an expansion of the categories considered in the analysis compared to previous editions. For this reason, McKinsey emphasizes, the figure is not directly comparable to the previous estimate of $2.000 trillion. In the United States, the market alone is worth over 700 billion of dollars and is growing at an estimated rate of 5 to 10% per year.
Wellness becomes an investment sector
It is precisely the speed of growth that make wellness increasingly interesting for capitalAccording to McKinsey, the six largest deals with a health and wellness component since 2021 were all announced or closed in 2025 or later, for a total value of nearly $89 billion. This data suggests a shift in pace: wellness. it is no longer considered just a niche of mass consumption, but as a market capable of attracting operations of significant size.
Investor interest fits into an ecosystem that encompasses health, nutrition, fitness, beauty, and services dedicated to performance and longevity. The research considers global transactions announced or closed between January 2021 and September 2026, with a value of at least $300 million, in consumer-facing segments of appearance, fitness, health and nutrition, including private equity transactions.
From supplements to longevity: the scope expands
The transformation of the sector is also evident in consumer behavior. Wellness is breaking out of traditional boundaries and involves nutrition, beauty, travel, social relationships and technologyAmong the most significant phenomena is the indirect effect of GLP-1 drugs, which is also changing adjacent categories. Among consumers who report taking these drugs, 35% say they eat more protein, 19% have added supplements to their routine, and 18% have started or intensified strength training.
At the same time, interest is growing in wearable devices, home diagnostics, biomarkers, social saunas, cold plunges, and biohacking practices. The common denominator is the desire to no longer limit oneself to "feeling good", but to actively optimize their health. Consumer diagnostics also offer significant potential. More than half of consumers who purchased products or services such as home testing kits, advanced imaging, or biomarker panels in the past year say they intend to increase their spending in these areas in the next twelve months.
Demand is growing, but so is the bar.
The market, however, has not yet fully met expectations. Around 40% of consumers globally believe that current wellness offerings are still insufficient, especially in sectors of longevity, mental health and mobilityThis creates space for new products and services, but also presents a challenge for companies: simply building a promise of well-being is no longer enough. Consumers demand results.
In the United States, price and effectiveness are listed as the main purchasing factors for wellness products, followed by quality. For consumers who spend more, effectiveness and quality take on even greater weightIn other words, the growth of the sector does not mean that every wellness product automatically has a market: the ability to demonstrate a concrete benefit becomes a decisive competitive element.
AI also enters the value chain
Another factor set to change the industry is artificial intelligence. More than half of the consumers surveyed uses AI for wellness-related activities, from product recommendations to meal planning, to understanding health data and information. The report, however, highlights a significant limitation: use does not automatically equate to trust. Forty percent of US consumers fear that AI-generated health advice may be inaccurate.
Furthermore, when it comes to deciding which products to buy, recommendations from friends and family, indicated by 35% of the interviewees, and those from health professionals, at 30%, remain much more influential than chatbots, stuck at 8%. For companies and investors, the consequence is clear: technology can become a key infrastructure for wellness, but scientific credibility and the ability to demonstrate product efficacy remain key.
An increasingly large and contested market
Wellness is therefore taking on the characteristics of a real growth engine for the consumerIn 2026, 33% of new consumer products launched in the US in the categories analyzed by McKinsey will feature a health and wellness promise, up from 24% in 2021. Furthermore, 53% of the fastest-growing brands—those with annual growth exceeding 20%—have a health and wellness-focused value proposition. The question is not just how large the sector is today, but how transversal it is destined to become. From nutrition to cosmeticsFrom digital devices to diagnostics, from fitness to longevity, wellness is becoming a platform capable of generating new markets and reshaping existing ones.
I nearly $89 billion concentrated in the six largest transactions With a wellness component since 2021, they represent, in this sense, more than just a statistic on M&A transactions. They are an indicator of capital's growing interest in a structural shift in consumption. Wellness, once a niche phenomenon, has now become a $2.700 trillion global market.