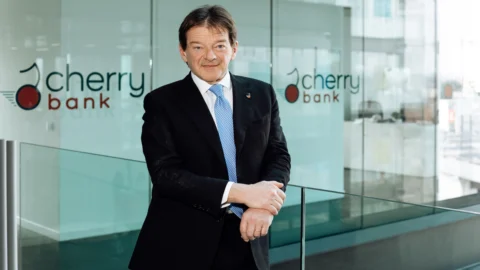
Cherry Bank closes first half of 2026 with a pre-tax profit of 38 million of euros, substantially stable compared to the 38,1 million of the same period of 2025. TheNet income It stood at 23,56 million, down 6,1% from 25,1 million a year earlier. "The results for the first half of 2026 are positive and slightly above the expectations of our 2026-2028 Strategic Plan," commented the founder and CEO. John Bossi, highlighting the growth of new businesses and the repositioning process started last year. “A progressive review of the business model has been underway since 2025 according to clear and coherent guidelines: development of the Factoring and special finance for businesses, consolidation of the Relationship Bank model thanks to the services of Private & Wealth Management and to the Retail network,” Bossi explained. “The new businesses show growth momentum and confirm that the direction we've taken is right” and will allow, in the coming months, “to consolidate our role as a partner of choice for entrepreneurs and their businesses.”
Cherry Bank, first half of 2026: interest margin and commissions increase
Il intermediation margin stood at 102,2 million euros, down 2% compared to 103,8 million in the first half of 2025. The result was affected by the progressive reduction in the contribution of tax credits, while net of this component the margin grew by 7%. interest margin rose 63% to 25,2 million, the net commissions by 51% to 10,5 million, also supported by the development of Factoring and Private & Wealth Management. Net profit from trading activities, however, decreased by 39% to 21,1 million. operating costs fell 1% to 57,9 million.
Overall, pre-tax profit remained at 38 million, with a Roe by 20,4%. After taxes, net profit fell to 23,56 million.
More credit to businesses, growing assets and collections
- core net loans grew by 3%, supported by the Corporate & Investment Banking (+35%) and from Factoring (+79%). During the first half of the year, Cherry Bank also strengthened its CIB with new specialized skills. Customer loans rose 10% to €3,54 billion, while total assets reached €4,65 billion, up 2% compared to the end of 2025.
Assets under management are also growing: assets under management reached 1,4 billion euros (+18%), of which 939 million (+21%) in Private & Wealth Management, equal to approximately 66% of the total. As of June 30, the area had 31 relationship managers and has expanded its offering with new agreements with international partners.
La harvesting Total deposits rose 1% to €4,3 billion. Deposits through the branch network grew 22% to €1,2 billion, while online deposits increased 18% to €709 million. On the retail front, Retail, the bank has continued to develop its collection and lending operations. The network now includes 24 branches and 13 offices, following the opening of the Milan office in June 2026.
More solidity and strategy towards 2028
The strengthening of the business is also reflected in the financial position: net equity rose to 243 million euros, while the CET1 ratio went from 16,30% at the end of 2025 to 17,15%, with an increase of 85 basis points. TheLCR remains high, at 303,8%.
The 2026-2028 Strategic Plan envisages a progressive reduction in the contribution of tax credits, which still have a positive impact on profitability but are expected to decline until 2028. The goal is to completely replace them with the growth of Factoring, Corporate & Investment Banking, and special finance for businesses.
At the same time, Cherry Bank maintains a rigorous and selective approach to npl, focusing on the profitability of operations, rapid capital turnover and the optimization of capital impacts.