Le European stock exchanges they are struggling downwards, although remaining close to their highs, following theWall Street opens negatively, despite the Use macro data encouraging: GDP for the second quarter of 2025 has been revised upwards to +3,8%, above expectations of 3,3%, while the first quarter went from -0,5% to -0,6%. Meanwhile, expectations are growing for theinflation pce, coming tomorrow, a key indicator for the Fed and for understanding its next moves on rates.
On the sector front, the spotlight remains on tech stocks and the chip sector, with AI taking center stage. Nvidia e Oracle infrastructures pay tribute to fears about the cyclical nature of the sector, amplified by the partnership with OpenAI, while Oracle infrastructures launch one fundraising through corporate bonds. Also Starbucks comes under pressure after announcing the closure of some stores and the reduction of 900 jobs in North America.
Read EVEN Stocks: There's a fear of missing the train. di G. Bruschi
A Business Square, the banks remain in the spotlight. Ps e Mediobanca confirm themselves as protagonists of the banking risk, while the government could impose conditions on a possible alliance between Bpm bank , Italian branch of Crédit Agricole, on which Minister Giorgetti recalled that the government will be able to impose conditions. Banco BPM also benefits from positive coverage from Goldman Sachs. Fitch has revised its ratings upwards. Intesa Sanpaolo e Unicredit, the latter also benefits from an increase in the target price by Goldman Sachs and brings forward the Board of Directors' meeting for the approval of the third quarter accounts (to October 21st from 27th). Campari records a target price update from Equita.
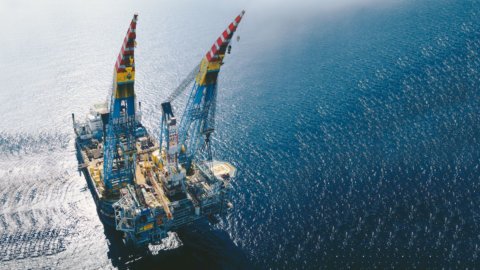
Among the main titles stand out Saipem, following the green light for the cross-border merger with Subsea 7, Tim e Stellantis, the latter supported by European registration data. At the end BRUNELLO CUCINELLI (-4,95%), suspended from trading after the sell-off linked to Morpheus Capital's accusations of alleged sales in violation of EU sanctions in Russia. Also weak pharmaceuticals, which is threatened by new US tariffs. Outside the main basket, Mfe closes the first half of the year with a declining operating result, but with an increase in net profit.
The 10-year BTP yields 3,61%, with the spread to 86 points. Euro balance at 1,175 on dollar. Petroleum little changed: Brent above $69/barrel, WTI at $65. Gold up to 1.745 d/oz.